What happened in China this week:
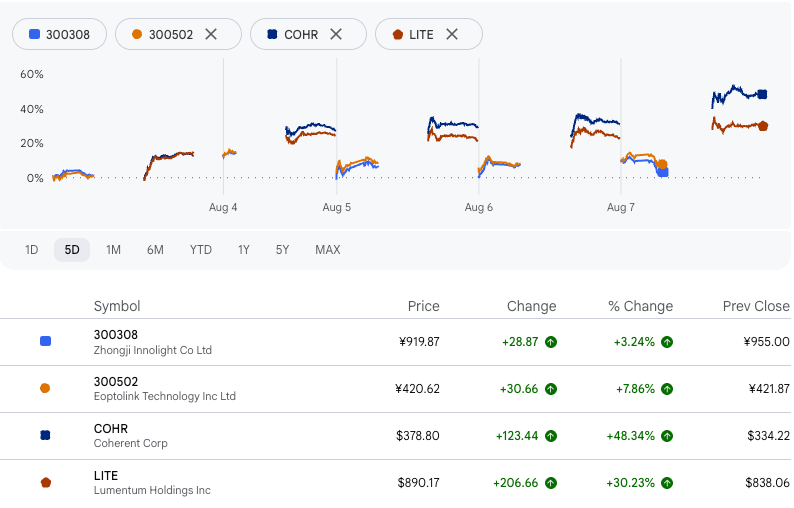
US Ban On Chinese Optical Chips Was Supposed To Hurt Innolight and Eoptolink. Their Stocks Say Otherwise.
AIA, Prudential, HSBC and StanChart Fall After China Taxes Offshore Insurance Policies
China Continues To Cut EV Subsidies. Carmakers Are Heading Abroad, and BYD Is Betting On Robotics
Haidilao Launches Burger Chain. We Think It’s a Mistake.
WuXi AppTec Stock Jumps 20% This Week After Showing 39% Revenue Growth in 1H26
#1 US Ban On Chinese Optical Chips Was Supposed To Hurt Innolight and Eoptolink. Their Stocks Say Otherwise.
The US Federal Communications Commission is drafting a ban on imports of new Chinese optical transceivers, the latest move in its push to cut America’s reliance on China’s AI supply chain. The stated aim is national security. The likely near term effect is disruption, because Chinese manufacturers dominate global production of these modules.
Zhongji Innolight and Eoptolink alone account for a substantial share of global 800G and 1.6T transceiver shipments (industry shorthand for modules that move data at 800 gigabits and 1.6 terabits a second), and that gives them a scale, engineering expertise and cost advantage that Western suppliers still can’t match.
In the near term, the pain is more likely to land on US hyperscalers than on Chinese manufacturers. Amazon, Microsoft and other AI infrastructure builders rely heavily on Chinese optical modules to wire together the thousands of GPUs inside their data centres. Western suppliers simply don’t have the production capacity to close that gap for the next one to two years. A sudden ban could trigger supply bottlenecks, push up component costs, hurt GPU utilisation and delay data centre rollouts.
The restrictions could also spill into broader networking gear such as switches, co-packaged optics (CPO) and near-packaged optics (NPO), the next generation designs that mount the optical engine directly on or near the switch chip to save power and space. That pushes the disruption well beyond standalone transceivers.
China isn’t losing much sleep
For Chinese optical companies, demand remains enormous regardless. Beijing and state linked funds have also poured significant capital into propping up these strategically important businesses. On top of that, the US now accounts for a much smaller share of China’s optical module exports than it once did, with demand shifting toward Southeast Asia, particularly Malaysia, where AI data centre investment is accelerating. Chinese suppliers are also expanding manufacturing in Southeast Asia, both to diversify production and to get ahead of future US sourcing rules.
Over the longer run, these restrictions look more likely to accelerate a bifurcation, or split, of global AI supply chains than to eliminate China’s role. Chinese firms may lose share in the US, but expect them to deepen their presence in China and other markets while continuing to expand capacity. US cloud providers, meanwhile, will diversify suppliers and build alternative manufacturing bases outside China. Full supply chain independence, though, will take years and a lot of capital.
Net effect, the policy is unlikely to meaningfully weaken China’s optical industry in the near term. What it will do is raise costs, fragment global supply chains, and reinforce the broader technological decoupling between the world’s two largest economies.
The market shrugs it off
This week, Chinese optical stocks climbed alongside their Western counterparts Coherent and Lumentum. The two US names gained far more, likely on hopes of a wave of new orders once Chinese parts are banned. But Innolight and Eoptolink rose too, just by smaller margins. The market’s message is that Chinese players won’t get hurt by the ban nearly as much as the headlines suggest.